

Maybe in the most characteristic move in the markets, oil prices continued to rise. US stock markets were able to stabilise, even gain at some points and in the FX market the main issue seems to be the weakening of the USD for the first time in four weeks.
MORNING OVERVIEW
Oil prices continued to rise yesterday and are about to end the week in the greens. Tensions in the Middle East are ongoing, as vessels are being hit at the Straits of Hormuz and Houthis are attacking Saudi Arabia. Also the resumption of Ukrainian attacks on Russian oil refineries are adding more worries for the supply lines of the international oil market. Thus oil market participants’ worries intensified, adding a premium to the commodity’s price. Should market worries be maintained or even intensify further, we may see oil prices continuing to rise.
MARKET SNAPSHOT
| MARKET | CURRENT | CHANGE | COMMENT |
| US 100 | 29938 | +0.01% | Nasdaq stabilises after drop |
| JP 225 | 65494 | +1.67% | N/A |
| EUR/USD | 1.1240 | +0.18% | Weakening USD allows the pair to rise |
| Gold | 4180 | +0.23% | Gold’s price remains relatively stable |
| Crude | 97.40 | -0.57% | Despite edging lower, oil prices have bullish tendencies |
KEY MARKET THEMES
01 — US stock markets gain
US equity markets staged a recovery yesterday, easing concerns about further declines, particularly within the technology sector. The Dow Jones Industrial Average rose by approximately 1%, while the technology sell-off came to a halt. The improvement in market sentiment appears to have been driven by a moderation in concerns surrounding the Federal Reserve, providing renewed support for US equities. On the flip side should the market’s worries for the AI sector and the Fed intensify we may see a more cautious approach emerging and weighing on US stock markets.
Market implication (Dow Jones): Bullish
02 — Oil prices maintain bullish tendencies
Oil prices continued to climb yesterday and are on track to finish the week higher. Ongoing tensions in the Middle East, including attacks on vessels in the Strait of Hormuz and Houthi strikes against Saudi Arabia, have heightened concerns over global oil supplies. Meanwhile, renewed Ukrainian attacks on Russian oil refineries are creating additional uncertainty in international energy markets. These geopolitical developments have intensified supply concerns, prompting market participants to demand a higher risk premium. If tensions persist or escalate further, oil prices could continue their upward trajectory in the coming days.
Market implication (Oil): Bullish
03 — US about to end the week with a loss
The USD is on track to close the week in negative territory, snapping a four-week winning streak. The greenback has come under pressure as market expectations for further Fed rate hikes have eased, despite consumer and producer inflation figures for the past month coming in above expectations. The Fed’s policymakers have yet to adopt a sufficiently hawkish stance, with Fed Chair Warsh notably avoiding any reference to the bank’s future interest rate path during today’s Asian session. It should be noted that further tightening of the banks’ monetary policy tends to restrict economic activity in the US, thus its understandable why the bank seems to hesitate. On the flip side, inflationary pressures are intensifying in the US economy adding more pressure on the Fed to hike rates. The market is currently pricing in, the Fed to remain on hold in its next meeting late October and proceed with a rate hike in December. A possible further easing of the market expectations for the Fed to tighten its monetary policy could weigh on the USD.
Market implication (GBP/USD) : Bullish
WHAT MATTERS TODAY
US Industrial production rate (MoM) for September
Time GMT+2): 16.15
Expected: 0.4%
Previous: 0.0%
Potential market reaction:
Could support USD
WHAT MATTERS on Monday’s Asian session
China’s GDP rate (YoY) for Q3
Time (GMT+2): 05:00
Expected: 4.4%
Previous: 4.3%
Potential market reaction:
Should the actual rate accelerate beyond market expectations we may see the risk on market sentiment being enhanced and riskier assets getting some support. Should the actual rates undershoot market expectations, we may see a more cautious approach emerging
ASSET FOCUS
[Dow Jones, Equities]
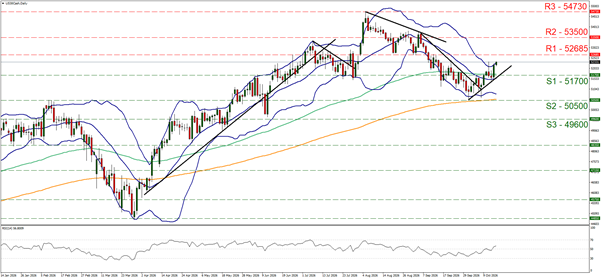
Dow Jones rose yesterday clearly breaking the 51700 (S1) resistance line, now turned to support. We maintain a bullish outlook for the index as a long as the upward trendline guiding it since the start of the month remains intact. We also note that the RSI indicator has risen above the reading of 50, implying a slight bullish predisposition of the market for the index, supporting our outlook. Should the bulls remain in charge, we may see Dow Jones aiming if not breaching the 52685 (S1) support line, With the next possible target for the bulls being set at the 53500 (R2) resistance level. For a bearish outlook to emerge, we would require Nasdaq to reverse yesterday’s gains, break clearly the prementioned upward trendline, in a first signal of an interruption of the upward motion of the index and continue to break also the 51700 (S1) support line and start actively aiming if not reaching the 50500 (S1) support barrier.
KEY LEVELS
- Resistance (R1): 52685
- Resistance (R2): 53500
- Support (S1): 51700
- Support (S2): 50500
Technical View: Bullish
CROSS-ASSET VIEW
| ASSET CLASS | BIAS | KEY DRIVER |
| US Equities | Neutral | Conflicting fundamentals provide a mixed picture |
| USD | Bearish | Fed monetary policy expectations |
| Gold | Neutral | N/A |
| Oil | Bullish | Oil market worries for the situation in the Gulf region push oil prices higher |
TRADING SPHERE VIEW
Bearish for USD
Our base case:
Easing expectations for the Fed to tighten its monetary policy tend to calm the markets, thus allowing for the USD to correct lower after a four week rally.
What would change our view:
Statements by Fed policymakers characterised by a hawkish tone, may take the markets by surprise, force them to reposition and thus providing support for the USD. Also a possible wider than expected acceleration of the US industrial output growth rate for September could somewhat brighten the US macroeconomic outlook thus providing some support for the USD in the FX market.
RISKS TO THE VIEW
Market expectations for the Fed to tighten its monetary policy re-enhanced
Should the market’s expectations for the Fed to tighten its monetary policy at a faster pace be rekindled, we may see the USD regaining some ground.
TODAY’S WATCHLIST
01 US September Industrial output rate
DISCLAIMER: This content is for general informational and educational purposes only and should not be considered investment advice or investment recommendation.