

The Democrats have managed to take control of both houses of Congress, resulting in what could be described as a blue sweep.
MORNING OVERVIEW
The RBA’s interest rate decision took place earlier on today in which the bank hiked by 25 basis points as widely expected. For today, market participants are shifting their focus to the US midterm elections where the Democrats are vying for control of Congress. For the European Equities markets, Michael Field the Chief European Equity Strategist at Morningstar, stated the following “The fears around the impact on European defence stocks are fair, but we still see significant value in the sector and believe the structural drivers underpinning higher defence spending and the requirement to restock by European nations are still being underappreciated by the market.”
MARKET SNAPSHOT
| MARKET | CURRENT | CHANGE | COMMENT |
| US 500 | 7645 | +1.02% | Democratic sweep |
| AUD/USD | 0.7015 | +0.71% | DXY |
| EUR/USD | 1.1247 | +0.50% | Eurozone HICP rates |
| Gold | 4043 | +2.84% | Democratic sweep |
| Brent | 101.74 | -1.79% | Will the US strike Iran this week? |
KEY MARKET THEMES
01 — The Blue wave has arrived
The US has seen a change in power from the Republicans to the Democrats in both houses, with the Blue sweep leading to the Democrats controlling the Senate and the House of Representatives. The Blue sweep has resurfaced concerns that the Democrats could increase regulatory scrutiny in the AI sector, which in turn could weigh on US stock markets. Moreover, the control of both houses could weigh on US Equities in general.
Market implication (USD): N/A
02 — Eurozone preliminary HICP rates come in as expected
The Eurozone’s preliminary HICP rates for October accelerate from 3.8% to 4.0% as was expected by economists. The uptick in inflation could provide support for the common currency as it may increase rate hike expectations for the ECB in order to combat the rising inflationary pressures in the economy. However, with ECB President Lagarde set to depart in a few months from her position, she may be reluctant to shake the boat so close to her departure. Thus we would focus on statements from other policymakers.
Market implication (EUR): Bullish
03 — ISM Non-Manufacturing PMI figure due today
The US ISM Non-Manufacturing PMI figure is set to be released during today’s American trading session. The figure for October is expected to decrease from 58.8 to 57.9 which could weigh on the greenback. In turn should the figure come in as expected or lower, it may weigh on the dollar.
Market implication (DXY): Bearish
WHAT MATTERS TODAY
US Midterm elections polls open
Time GMT+2): 24:00
Expected: N/A
Previous: N/A
Potential market reaction:
Volatility in the USD
ASSET FOCUS
[EUR/USD , FOREX]
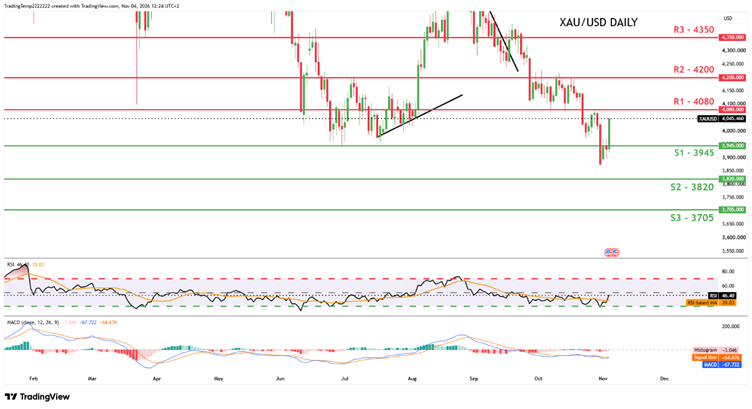
XAU/USD appears to be moving in an upwards fashion. We opt for a bullish outlook for the precious metals price. For our bullish outlook to be maintained, we would require a clear break above our 4080 (R1) resistance line with the next possible target for the bulls being our 4200 (R2) resistance line. On the other hand, for a sideways bias we would we would require the pair to remain confined between our 3945 (S1) support level and our 4080 (R1) resistance line. Lastly, for a bearish outlook we would require a clear break below our 3945 (S1) support level, with the next possible target for the bears being our 3820 (S2)
KEY LEVELS
- Resistance (R1): 4080
- Resistance (R2): 4200
- Support (S1): 3945
- Support (S2): 3820
Technical View: Bullish
CROSS-ASSET VIEW
| ASSET CLASS | BIAS | KEY DRIVER |
| US Equities | Neutral | Midterms |
| USD | Neutral | Midterms |
| Gold | Bullish | DXY |
| Oil | Bullish | Possible strikes on Iran this week |
TRADING SPHERE VIEW
Bullish for OIL
Our base case:
We wouldn’t be surprised to see oil prices moving higher this week, considering the possible strikes on Iran by the US next which have been floating around for a few days.
What would change our view:
No strikes on Iran this week
RISKS TO THE VIEW
Unexpected events
Peace deal or agreements with Iran
TODAY’s WATCHLIST
01 US ISM Non-Manufacturing PMI figure